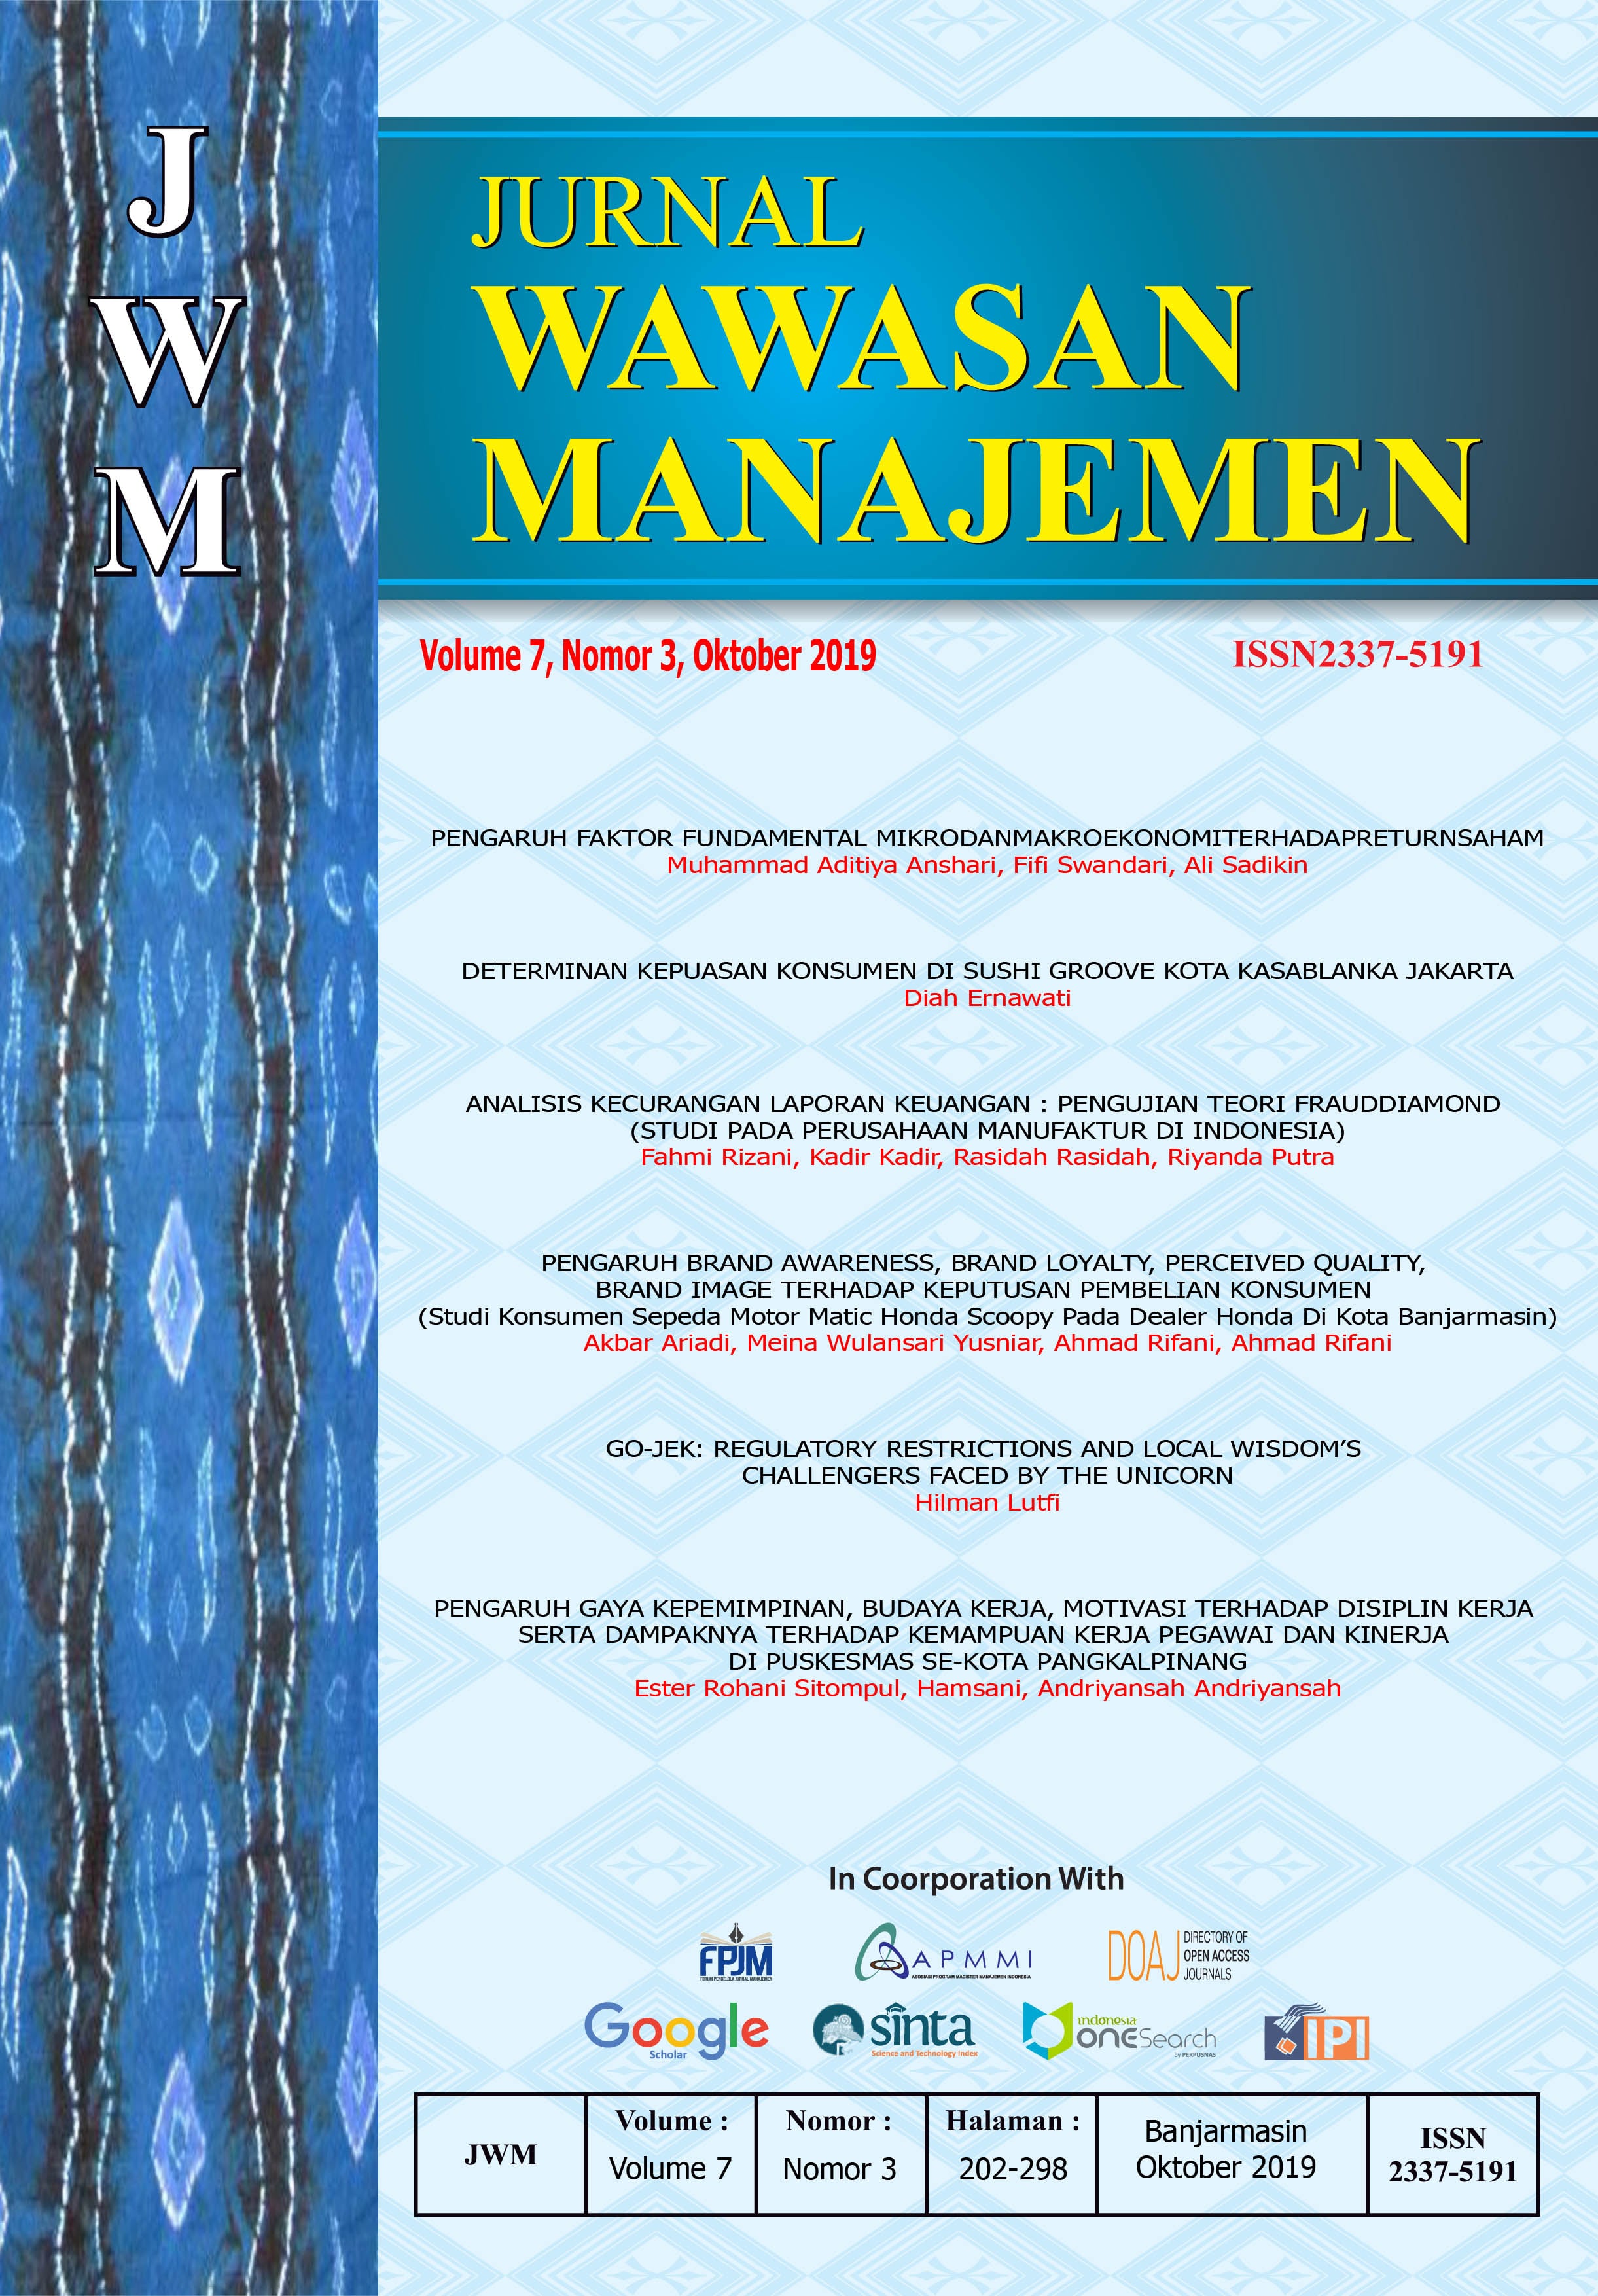
ANALISIS KECURANGAN LAPORAN KEUANGAN : PENGUJIAN TEORI FRAUDDIAMOND (STUDI PADA PERUSAHAAN MANUFAKTUR DI INDONESIA)
DOI:
https://doi.org/10.20527/jwmthemanagementinsightjournal.v7i3.57Keywords:
Fraud diamond, fraudulent financial statement, pressure, opportunity, rationalization, capabilityAbstract
This study aims to determine the factors that influence fraud in financial statements. Detection of fraudulent financial statements using the theory of Fraud Diamond in manufacturing companies listed on the Indonesia Stock Exchange in 2016-2017. Fraud Diamond proposed by Wolfe and Hermanson (2009). Four variables of fraud diamond were tested which consisted of pressure, opportunity, rationalization and competency. Pressure is proxied by financial targets, financial stability, external pressures and individual financial needs. Opportunities are proxied by the effectiveness of supervision and the nature of the industry. Rationalization is proxied by the change of auditors, and Competency (capability) is proxyized by the replacement of the board of directors. The research sample used was 70 manufacturing companies listing on the Indonesia Stock Exchange in the 2016-2017 period with 140 financial statements. Data were analyzed using logistic regression analysis. The results showed that the variables financial targets, financial stability, external pressures, individual financial needs of supervision, ineffective monitoring, the nature of the industry, change of auditors and changes in the board of directors did not have an influence on financial statement fraud. From the results of these studies indicate that all research variables studied at each manufacturing company have not been able to indicate financial statement fraud.
Downloads
References
AICPA. (2002). Consideration of Fraud in a Financial Statement Audit. Statement on
Auditing Standard No. 99.
Anthony, R. N., & Govindarajan, V. (2012). Sistem Pengendalian Manajemen (11 ed.). (F. K. Tjakrawala, & Krista, Trans.) Jakarta: Salemba Empat.
Ardiyani, S., & Utaminingsih, S. N. (2015). Analisis Determinan Financial Statement
Melalui Pendekatan Fraud Triangle. Accounting Analysis Journal.
Cressey, D. (1953). Other people’s money, dalam: “Detecting and Predicting Financial Statement Fraud: The Effectiveness of The Fraud Triangle and SAS No. 99, Skousen et al. 2009. Journal of Corporate Governance and Firm Performance. Vol. 13 h. 53-81
Ghozali, I. (2016). Aplikasi Analisis Multivariate dengan Program IBM SPSS 23.
Semarang: Badan Penerbit Universitas Diponegoro.
Ikatan Akuntan Indonesia. (2018). Standar Akuntansi Keuangan.
Kusumawardhani, P. (2013). Deteksi Financial Statement Fraud dengan Analisis Fraud Triangle pada Perusahaan Perbankan yang Terdaftar Di BEI. JURNAL AKUNTANSI UNESA, Vol 1, N0 3.
Nabila, A. R. (2013). Deteksi Kecurangan Laporan Keuangan dalam Perspektif Fraud Triangle (Studi Empiris pada Perusahaan Manufaktur yang terdaftar Di Bursa Efek Indonesia Tahun 2010-2011). Diponegoro Journal of Accounting.
Nauval, M. (2015). Analisis Fakator-Faktor yang Berpengaruh Terhadap Kecenderungan Financial Statement Fraud dalam Perspektif Fraud Triangle. Jurnal Ilmiah Mahasiswa FEB, Universitas Brawijaya Vol 3, No, 2.
Norbarani, L. (2012). Pendeteksian Kecurangan Laporan Keuangan dengan Analisis Fraud Triangle yang Diadopsi dalam SAS No. 99. Diponegoro Journal of Accounting.
Nugraha, N. D., & Henny, D. (2015). Pendeteksian Laporan Keuangan Melalui Faktor Resiko, Tekanan, dan Peluang (Berdasarkan Press Release OJK 2008-2012). e- Journal Akuntansi Trisakti Volume 2, Nomor 1.
Sekaran, U. (2009). Research Methods For Business. Jakarta: Salemba Empat. Sihombing, Kennedy Samuel dan Rahardjo, Shiddiq Nur. (2014). Analisis Fraud
Diamond dalam Mendeteksi Financial Statement Fraud: Studi Empiris pada
Perusahaan Manufaktur yang Terdaftar di Bursa Efek Indonesia (BEI) Tahun
-2012. Diponegoro Journal of Accounting Vol. 03 No. 02. ISSN (Online):
-3806.
Skousen, C. J., Smith, K. R., & Wright, C. J. (2009). Detecting and Predicting Financial Statement Fraud: The Effectiveness of The Fraud Triangle and SAS No. 99. Corporate and Firm Performance Advances in Financial Economics, Vol. 13.
Soselisa, R., & Mukhlasin. (2012). Pengaruh Faktor Kultur Organisasi, Manajemen, Strategik, Keuangan, Dan Auditor Terhadap Kecenderungan Kecurangan Akuntansi: Studi Pada Perusahaan Publik Di Indonesia.
Sukirman, & Sari, M. P. (2013). Model Deteksi Kecurangan Berbasis Fraud Triangle (Studi Kasus pada Perusahaan Publik Di Indonesia). Jurnal Akuntansi dan Auditing, 9.
Tiffani, L., & Marfuah. (2015). Deteksi Financial Statement Fraud dengan Analisis Fraud Triangle pada Perusahaan Manufaktur yang Terdaftar di Bursa Efek Indonesia. Simposium Nasional Akuntansi 18.
Wolfe, David T. and Hermanson, Dana R. (2004). The Fraud Diamond: Considering theFour Elements of Fraud. CPA Journal.Vol 74 Issue 12, hal. 1-5.
Downloads
Published
Issue
Section
License
Copyright (c) 2022 JWM (JURNAL WAWASAN MANAJEMEN)

This work is licensed under a Creative Commons Attribution 4.0 International License.